You walk into the storage room, see boxes everywhere… but still can’t find what you need. “We just ordered this—where is it?” Turns out, most small businesses are in the same mess. Interestingly, only about 48% are actively tracking their stock.
That kind of gap quietly eats into growth. Inventory control isn’t just counting boxes. It’s keeping products moving where they should be without draining time or cash. You don’t need big warehouses or pricey systems to get it right.
Stick with this checklist, and you’ll see exactly what to do, what to watch, and how to make your inventory run like clockwork.
Small Business Inventory Control Fundamentals for Growth
Growth slows when products run out or pile up where they’re not needed. That’s where small business inventory control comes in. It’s like running a distribution center without knowing what’s on the shelves. Orders get delayed, costs climb, and opportunities slip away.
And when the shelves are empty of what customers actually want? It’s not just an inconvenience, it’s lost business. Imagine a customer walks into your store looking for their favorite item, only to find it out of stock. Odds are, they won’t just wait for you to restock. In fact, research shows that 63% of shoppers who encounter out-of-stock inventory end up buying from a competitor or simply walking away empty-handed. That’s a double hit: you miss the sale, and your competitor gains a new fan.
The same idea works in business, without strong inventory tracking, you risk losing sales and higher costs. Small business inventory control keeps the right products moving at the right time.
But there’s another trap: excess stock. It’s tempting to buy in bulk for discounts or free shipping, but tying up too much cash in merchandise can quietly drain your business. Unsold goods, especially seasonal ones, turn into dead weight. (Just ask anyone trying to unload Christmas sweaters in January. You’ll be lucky to break even, let alone make a profit.) On top of that, extra inventory means extra costs for storage, insurance, and sometimes even markdowns that eat away your margins.
Getting inventory control right isn’t just about avoiding empty shelves. It’s about keeping your cash flowing, storage costs down, and making sure you never end up with a mountain of unsold stock collecting dust.
The right inventory tracking technology gives you real-time visibility and data to help you act fast. With consistent inventory control, you can track your inventory with confidence and keep your business ready for every order.
What Does a Stock Controller Really Do?
Think of a stock controller as your inventory quarterback. This person is the point guard for everything that moves in and out, from raw materials to your latest bestsellers. Their job is keeping a watchful eye on inventory levels so nothing falls through the cracks.
Instead of boxes piling up or going missing, a stock controller steps in to:
- Oversee all purchase orders and make sure incoming shipments match what was ordered.
- Check in deliveries and update records, so your numbers always match reality.
- Centralize responsibility for inventory, making it easy to spot errors before they become expensive problems.
If you handle a large volume of products or find yourself frequently losing track of stock, having one person in charge can streamline everything. The stock controller helps keep your inventory lean, accurate, and ready for action.
Essential Inventory Tracking Methods That Actually Work
Knowing what you have and where it is helps small business inventory control work at its best. The right inventory tracking method saves time and reduces errors. Modern inventory tracking technology offers options for every budget and business size.
The table below compares four common methods so you can see which one fits your needs.
| Method | Pros | Ideal For |
| Manual Spreadsheets | Low cost, simple to set up, easy for small product lists. | Very small businesses or startups with limited stock. |
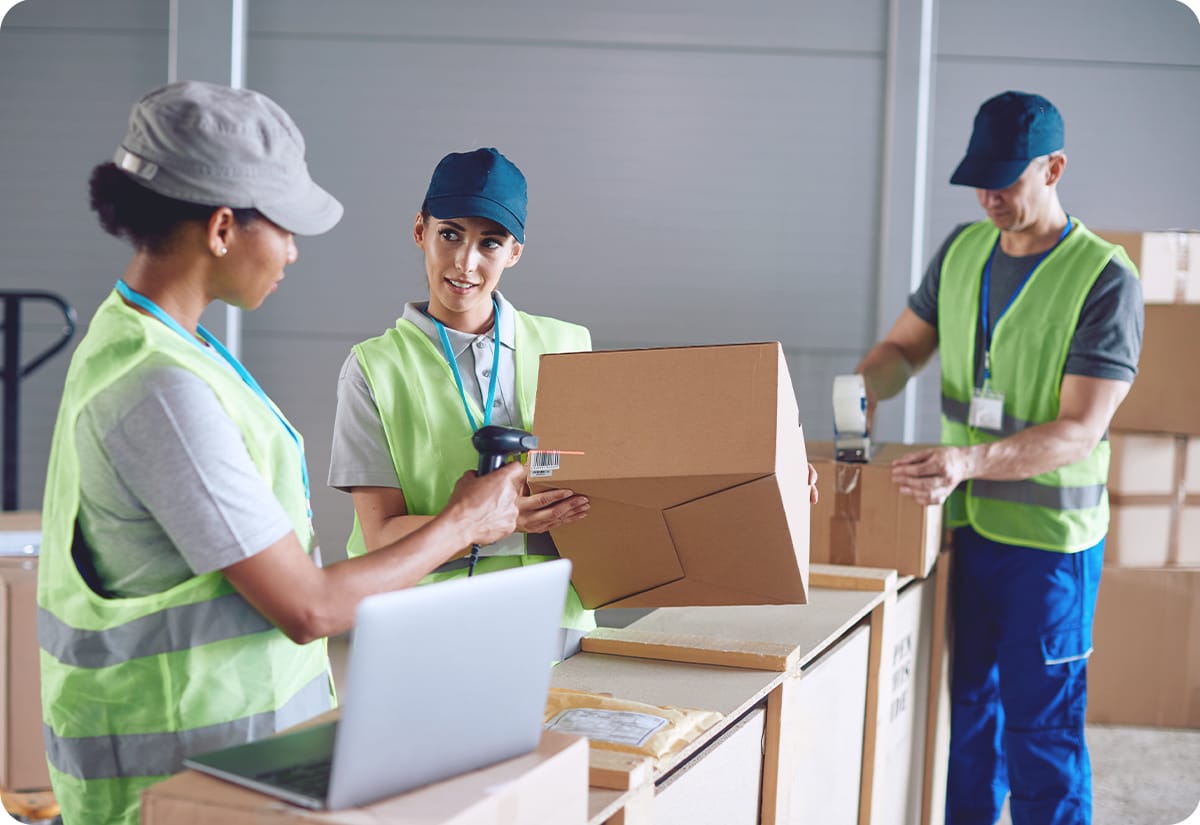
| Barcode Systems | Fast scanning, fewer mistakes, real-time updates with a barcode scanner. | Retail stores and warehouses that need to track stock daily. |
| RFID | Reads multiple items at once, offers real-time location data. | Businesses with high-value products or large stock levels. |
| Integrated ERP System | Combines inventory management system with finance and supply chain tools. | Growing companies that want to automate and manage their inventory in one place. |
Small business inventory control improves when the right inventory tracking technology matches business needs. Testing different inventory tracking tools can help you find the best fit before you scale.
Barcode systems only work as well as what’s actually printed on the label, though, which starts with how you identify each product in the first place.
How to Put Inventory Tracking Into Action
No matter which method you choose, the process generally follows a few consistent steps:
- Start with an Item Library: Create a master list of all inventory items. This can be as simple as a spreadsheet or as robust as an inventory management dashboard.
- Enable Item Tracking: Assign each product its own line in your system. For each item, record starting quantities and update as you receive, sell, or move stock. Many systems allow you to track inventory at multiple locations—a must if you have more than one site or stockroom.
- Bulk Uploads and Updates: When you’re dealing with a larger product list, importing and updating inventory in bulk can save hours. Most inventory management tools let you download your current inventory report, make changes (like updating stock counts or enabling low-stock alerts), and upload it back in one go.
- Set Stock Alerts: Enable low-stock or sold-out alerts for each product. This way, you’re notified when it’s time to reorder before you run out—no more scrambling or disappointing customers.
Barcode systems only work as well as what’s actually printed on the label, though, which starts with how you identify each product in the first place.
ABC Inventory Analysis: Focusing on What Matters Most
Trying to keep every last nut and bolt under a microscope usually ends up wasting more time than it saves. That’s where ABC inventory analysis comes in. It’s a method that helps small businesses tighten control where it counts, on the inventory items that have the biggest impact on your bottom line.
The idea is simple: group your stock into three categories based on how much each item contributes to your annual sales value.
- A-items are your heavy hitters, the high-value products that make up a small portion of your total inventory, but a big chunk of your costs or sales (think: that pricey espresso machine versus packets of napkins). These deserve the closest attention, more frequent counts, and stricter ordering controls.
- B-items are mid-tier. They take up a moderate amount of space and spend, needing balanced attention without going overboard.
- C-items are the bulk buys, lower-cost parts or products you sell in high volume but that don’t tie up much cash. These just need basic monitoring to prevent overstock or running out unexpectedly.
Here’s how the breakdown usually looks in practice, based on best-practice guidelines (such as those from Lokad):
Classification % of Items % of Annual Consumption Value A 10-20% 70-80% B 30% 15-25% C 50% 5% By sorting products this way, you know where a small oversight could cost the most, and you can save your time (and sanity) by not sweating the small stuff. This keeps your inventory control efforts focused and effective, so you’re always giving the most attention to what matters most.
How Automation and AI Streamline Inventory Management
Automation and artificial intelligence are quietly revolutionizing how small businesses handle inventory—no robots required. Imagine software that automatically updates your stock counts the moment you make a sale, or that flags low inventory without you having to double-check the shelves.
Here’s how these smart tools help:
- Automatic Stock Updates: Real-time syncing means your inventory records are always up to date, cutting out hours of manual entry, and the errors that can sneak in late at night.
- Predictive Reordering: With AI analyzing trends and patterns, you’ll get prompts to restock before that popular item sells out, not after.
- Fewer Stockouts: Automated triggers catch dipping stock levels early, helping you avoid awkward “out of stock” moments at checkout.
- Time Savings: Let technology handle the repetitive work, so you can spend more time serving customers or growing your business.
- Smarter Insights: AI spots seasonality and buying habits you might miss, helping you buy smarter and stock what actually sells.
With automation and AI doing the heavy lifting, small business owners can manage more inventory with less hassle, no need for a huge tech budget or a dedicated IT person.
Why Product Identification Systems Matter
A clear product identification system is one of the simplest upgrades a small business can make to its inventory process. Assigning every item a SKU or barcode removes the guesswork the moment you’re searching for stock, updating counts, or fulfilling an order. Here’s why this small step makes such a big difference for small business inventory management.
Labeling your products with clear identifiers cuts down on mix-ups and lets you spot missing or misplaced products in seconds. With barcode scanning at checkout or during a stock count, physical inventory counts go from a guessing game to a quick, accurate process, and your inventory records stay reliable without extra manual work.
For a small business owner juggling lots of moving parts, this means fewer headaches and faster turnaround. Whether you use printed barcodes, manually assigned SKUs, or a combination of both, giving each product its own identifier is a straightforward way to keep your shelves organized, track inventory accurately, and keep fulfillment running smoothly.
Many inventory management platforms built for small businesses now support barcode scanning out of the box, so getting started doesn’t require a big upfront investment.
Pair a good product identification system with the right inventory management tool, and it pays off the moment your business grows past a spreadsheet.
Building Strong Inventory Control Systems Step by Step
Strong systems do not happen by accident. You need a clear plan that works for your products and your process. These steps will help you build a system that keeps stock in order and supports growth.
Step 1: Assess What You Have
Start with a full count of inventory items. This shows your current stock level and highlights gaps. A local café, for example, might find it has too much coffee syrup but not enough cups.
Step 2: Set the Right Quantity for Each Item
Decide the minimum and maximum amounts for each product. This prevents overstock and shortages. A clothing store may set a rule to keep 20 units of each top-selling size.
Step 3: Choose Your Inventory Tracking Technology
Pick a tool that fits your business needs and budget. The right option gives real-time updates and accurate inventory data. A small retailer might use cloud-based inventory management software to track stock and sales from one screen.
Look for features like real-time sales analytics, automated stock level adjustments when a sale is made, and daily stock alert emails so you always know if something’s running low or out of stock. These tools help you stay ahead of shortages, cut down on manual tracking, and make smarter restock decisions. With cloud-based systems, you can access your inventory status from anywhere, whether you’re in the shop, at home, or on the go.
Step 4: Create a Simple Process for Receiving Stock
Log every shipment when it arrives. Check quality control and update stock levels right away. A bike shop might scan each part into its system the moment it is unloaded.
Don’t Overlook Quality Control
No matter what you sell, it’s essential to ensure all your products look great and are in working order. Quality control can be as straightforward as having employees quickly examine each item during stock audits, using a checklist for signs of damage and correct product labeling. Spotting issues early keeps your shelves, and your customers, happy.
Step 5: Schedule Regular Audits
Set a time to count your inventory and match it to system records. This helps catch errors and inventory shrinkage before it grows. A local hardware store might do this once a month for high-value tools.
Even with the best inventory management tools, it’s important to physically count your stock on a regular basis. There are a few ways to approach this:
- Annual full inventory: Once a year, count every single item in your inventory. This gives you a clear baseline and highlights any big discrepancies.
- Ongoing spot-checks: For items that move quickly or have a history of stocking issues, conduct periodic spot-checks. This could mean counting a few key products each week or month to make sure your records stay accurate.
Mixing full counts with spot-checks lets you catch problems early and keeps your system honest, without shutting down your whole operation for a massive inventory event.
Understanding Inventory Shrinkage and Its Causes
Inventory shrinkage happens when your recorded inventory levels don’t match what’s actually on the shelf. For small retail businesses, this gap can add up quickly, leading to lost profit and confusion at audit time.
Shrinkage is usually caused by a handful of familiar culprits:
- Shoplifting: Customers taking products without paying is the most common reason inventory comes up short.
- Employee Theft: Sometimes losses happen internally, whether through misuse or intentional theft.
- Paperwork Errors: Mistakes in tracking shipments, recording sales, or logging returns can skew your numbers.
- Supplier or Vendor Fraud: Rarely, your partners might send fewer products than invoiced or swap higher-value items for similar-looking stock.
- Damage: Broken items—either in transit or on the sales floor—end up as losses too.
Some shrinkage slips through for unknown reasons, which is why regular audits and clear processes are key. Even though industry averages hover around 2% loss, any shrinkage hits you twice—once when you pay for missing or damaged products, and again when you lose the chance to sell them. Keeping these causes in check is one of the simplest ways to boost your bottom line.
Step 6: Train Your Team to Follow the Process
Everyone should know how to track inventory and update records. This ensures the process works even when you are not on-site. A bakery might train all staff to scan ingredients when used.
Step 7: Review and Improve the System
Look for trends in your reports. Adjust your inventory tracking technology or reorder points based on the data. A seasonal gift shop may lower stock levels after the holidays to cut costs.
Setting the right quantity for each item, from Step 2 above, gets a lot easier once you know which costing method your business should actually be using.
Improving Inventory Forecasting Accuracy
Getting your inventory numbers right starts with knowing what’s coming and going, and why. Improving your forecasting is less about crystal balls and more about smart habits. Here’s how you can dial it in:
- Look at Your Historical Data: Dive into past sales records to spot trends and recurring patterns. What sold out last summer? What sat on the shelf in December?
- Monitor Market Trends: Stay updated on your industry and what competitors are doing. Changes in customer preferences or economic shifts can impact demand.
- Factor in Seasonality and Promotions: If you run specials or see spikes around certain holidays (think back-to-school season for bookstores), adjust your forecasts accordingly.
- Use Tech to Your Advantage: Take advantage of inventory management platforms that offer built-in analytics to help highlight your best, and worst, performing products.
- Talk to Your Team: Staff on the floor often spot shifting customer demands before reports catch up. Regular check-ins with them can help you spot trends early.
- Adjust for Business Growth: If you’re expanding or rolling out new products, work those changes into your projections so you aren’t caught off guard.
With these strategies in place, you’ll have a much clearer sense of how much to order and when, making it easier to set those ideal stock levels and keep your shelves stocked just right.
Spotting and Dealing with Slow-Moving Inventory
One key to staying profitable is knowing when certain products just aren’t moving. Low-turn or “dusty” stock quietly eats up shelf space and cash, so it pays to know how to find it and what to do next.
Start by running sales reports or reviewing inventory turnover formulas from your tracking system. If an item hasn’t sold in six months or more, mark it as slow-moving. Once identified, you’ve got a few smart moves:
- Run special promotions: Discount the item or bundle it with top sellers to encourage sales and free up space.
- Seasonal sales or clearance events: Clear out inventory during major retail events to attract deal-seekers.
- Donation or return to supplier: If products linger despite efforts, consider donating to local organizations (for tax deductions) or negotiating a supplier return.
Regularly reviewing slow-turning inventory keeps your shelves agile, your working capital available, and your energy focused on products that grow your business most.
Inventory Management Tips for Businesses That Manufacture Their Own Products
If your business creates products from scratch, think handmade candle makers, small-batch food producers, or boutique furniture workshops, your inventory system needs to keep tabs on more than just finished goods. Instead, you’re tracking three main types of inventory:
- Raw materials: The basic items you’ll turn into finished products (like fabric for a bag maker or flour for a bakery).
- Work-in-progress (WIP): Items currently being made but not quite ready to sell (partially assembled chairs, dough proofing in the kitchen).
- Finished goods: Products that are complete and ready for your customers.
For makers and manufacturers, here’s how you can keep your inventory in check and avoid the classic trap of overproduction:
- Separate inventory types: Maintain separate records for raw materials, WIP, and finished products. This gives you a clear view of where your supplies, and your money, are tied up.
- Practice regular checks: Schedule routine counts of both raw materials and finished goods, not just what’s on the shelves. This will help prevent costly surprises or shortages in production down the road.
- Forecast carefully: Use sales history to estimate how much to produce. Avoid ending up with piles of unsold stock or running out of a key ingredient in your busiest season.
- Monitor usage rates: Track how quickly you use each raw material. Adjust reorder points so you never run out or over-invest in slow-moving supplies.
- Control work-in-progress: Set limits on how many items can be in production at once, so your workbench or kitchen doesn’t get overcrowded and your process stays manageable.
Learning from big-company missteps, like excessive write-offs due to poor forecasting, helps underscore the importance of steady checks and balanced production. By building these habits into your day-to-day process, you’ll keep cash flow healthier and production running smoothly, no matter how creative or customized your products may be.
Bulk Uploading Inventory Data: A Simple Step-By-Step Guide
When your product list starts to sprawl and manual updates become a chore, bulk uploading can be a game changer. Here’s how small businesses can quickly refresh inventory quantities across multiple items, without endless data entry or headaches.
- Start with an Inventory Export:
Begin by exporting your current item list from your inventory management system. Most platforms let you download this as a spreadsheet, think CSV files that open easily in Excel or Google Sheets. - Update Quantities in Bulk:
In the spreadsheet, locate the column for inventory quantities and adjust the numbers for each product as needed. This is also a good chance to review things like stock alert thresholds and make updates in one fell swoop. - Save and Double-Check:
Once all updates are made, save your sheet. It’s wise to scan for errors, like typos or missing data, before moving on. - Re-import the File:
Upload your updated file using your inventory system’s import tool. Usually, this just means dragging and dropping the file into the platform and confirming the changes. - Verify the Update:
After the upload, review your dashboard or item library to make sure everything looks right. This step ensures you catch any missteps before they cause problems on the sales floor.
Bulk uploading is especially handy for restocking after big orders, adding new products, or syncing locations—all without slowing you down.
What Are the Main Inventory Costing Methods for Small Businesses?
You don’t need a background in accounting to get a handle on inventory costing, just a clear rundown of the basic approaches. Four methods make up most of what small businesses actually use to keep inventory numbers meaningful and tax season less stressful. Here’s a quick guide to each one and which small business needs it tends to fit best.
- First-In, First-Out (FIFO): The stock you bought first ships out first. It’s a natural fit for businesses dealing with expiration dates; think bakeries, grocers, or anyone with products that don’t improve with age. FIFO keeps your oldest stock moving before it risks spoiling, and it tends to reflect a more current cost in your books when prices shift.
- Last-In, First-Out (LIFO): The opposite of FIFO, LIFO sends your newest inventory out the door first. Businesses that carry goods with a long shelf life, like hardware stores or furniture shops, often use it to manage accounting during periods of rising costs. When prices rise, LIFO records those higher costs upfront, which can lower taxable income. It’s worth noting LIFO isn’t accepted everywhere in the world; IFRS followers will need a different method.
- Just-in-Time (JIT): JIT keeps inventory lean by ordering only what you need, when you need it, cutting down on carrying excess inventory and costs. It’s popular with businesses short on storage space. The trade-off: it depends on supply chain partners you trust, since any hiccup in delivery or demand forecasting can leave you empty-handed at the wrong moment.
- Economic Order Quantity (EOQ): EOQ is the formula for cutting down on both storage and ordering costs. It calculates the optimum quantity to order, helping businesses with steady sales, like office supply dealers or local wholesalers, find the balance between too much and too little inventory on hand. Get it right, and cash keeps flowing without shelves sitting overstocked.
Exploring Drop Shipping as an Inventory Strategy
Drop shipping flips the traditional inventory model on its head: instead of stocking products yourself, you sell items that are held and shipped directly by your supplier or manufacturer. This means your business never physically handles the goods, orders placed through your store are sent straight to the wholesaler, who then fulfills them on your behalf.
This strategy can be a lifesaver for small businesses or startups facing space constraints or wanting to sidestep the upfront investment and ongoing costs of holding inventory. For example, an online retailer with a wide product catalog might use drop shipping to offer variety without tying up cash in extra stock. However, drop shipping isn’t just for digital stores, service-based businesses adding products, custom print shops, or brick-and-mortar retailers wanting to expand offerings without new storage space can also find it useful.
Keep in mind, while drop shipping lets you focus on sales and customer experience, it relies heavily on your suppliers’ reliability for quality and timely shipping. Clear communication and trustworthy partners, think established wholesalers or platforms like Oberlo and AliExpress, are key to making the model work smoothly.
Can You Deduct Inventory Shrinkage on Your Taxes?
Damaged, lost, or stolen inventory, known as shrinkage, is an inevitable part of running any retail business. The bad news: shrinkage eats into your profits in two ways. Not only do you lose the value of the product itself, but you also lose the potential sales revenue that item could have generated.
Now for the better news: in many cases, the IRS does allow you to deduct inventory shrinkage, including losses from theft or casualty, as part of your cost of goods sold (COGS) when filing taxes. This means that if products are damaged in transit, lost in the back room, or fall victim to sticky fingers on the sales floor, you may be able to account for those losses and reduce your taxable income accordingly.
Here’s what you need to keep in mind:
- Accurate Tracking: You’ll need reliable records to support your claim, including inventory counts, receipts, and documentation of the loss.
- Consult Your Tax Expert: U.S. tax rules can get tricky, and requirements vary for different business structures. Partner with a certified tax advisor or accountant (think: an Enrolled Agent or CPA) to be sure you’re handling these deductions by the book.
- Not Worldwide: If you follow international accounting standards, like IFRS, used outside the U.S.,the rules for deducting inventory shrinkage may differ.
Bottom line: Track inventory closely and don’t just chalk up shrinkage as an unavoidable hit. With careful documentation, you might ease the impact come tax season.
Choosing the Right Inventory Tracking Technology for Your Business
The right tool can make small business inventory control easier to manage and more accurate. Choosing the best option starts with knowing what matters most to your process. The right inventory tracking technology should fit your needs now and scale with your growth.
1. Budget
Decide what you can spend without hurting cash flow. Look for software solutions that match your needs without adding high software costs.
2. Scalability
Pick a system that works now but can handle more products in stock as you grow. This supports small business inventory control over the long term.
3. Ease of Training
Your team should learn it fast. Good inventory management depends on everyone knowing how to manage stock levels and update them in real time.
4. Integration with Existing Tools
Choose inventory tracking technology that connects with your current POS system or accounting software. This reduces extra work and keeps the inventory management process smooth.
5. Support and Reliability
Look for a provider that offers strong customer support and regular updates. This helps businesses avoid downtime that could lead to lost sales.
6. Reporting Features
A good system gives you clear data to help you make decisions. Use reports to track inventory more efficiently, reduce excess inventory, and keep the right quantity of each product.
Take Control of Your Stock, One Step at a Time
Like you, we know how stressful it is when stock sits in the wrong place or runs out right when demand spikes. We understand how these gaps can slow down orders, strain your team, and impact customer trust.
At Supply Chain Solutions, we help businesses strengthen small business inventory control through smarter supply chain planning and advanced inventory tracking technology. Our tools give you real-time visibility into stock levels so you can make fast, confident decisions. We work with you to design a process that moves products where they’re needed, reduces delays, and supports growth.
Contact us today to put a smarter, more efficient inventory process in motion.